Financing an ADU should not be the last question. It should be part of the early planning.
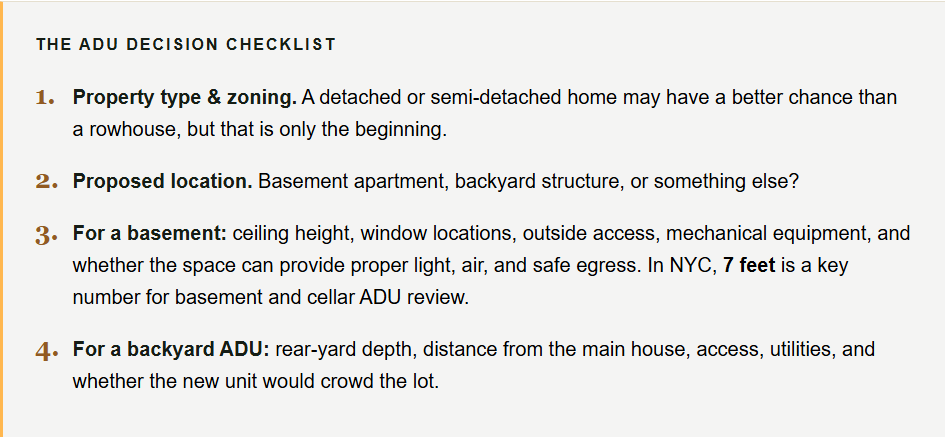
Before calling an architect or contractor, a homeowner should go through a basic ADU decision checklist. This does not replace professional review, but it helps you become a more informed owner.
I was working through an early ADU review for a family in Staten Island. Their home looked promising at first: a one-family detached house, the lot was larger than many NYC properties, and they had a rear yard that seemed deep enough to explore an ADU.
But the checklist quickly showed why homeowners should slow down before calling a contractor.
For the Staten Island family, the basement option needed a closer look at ceiling height and egress. The backyard option needed rear-yard depth and utility runs evaluated against zoning.
The family started with one question: "Can we build an ADU?" By the end, they understood the better question:
"Which ADU option survives the checklist?"
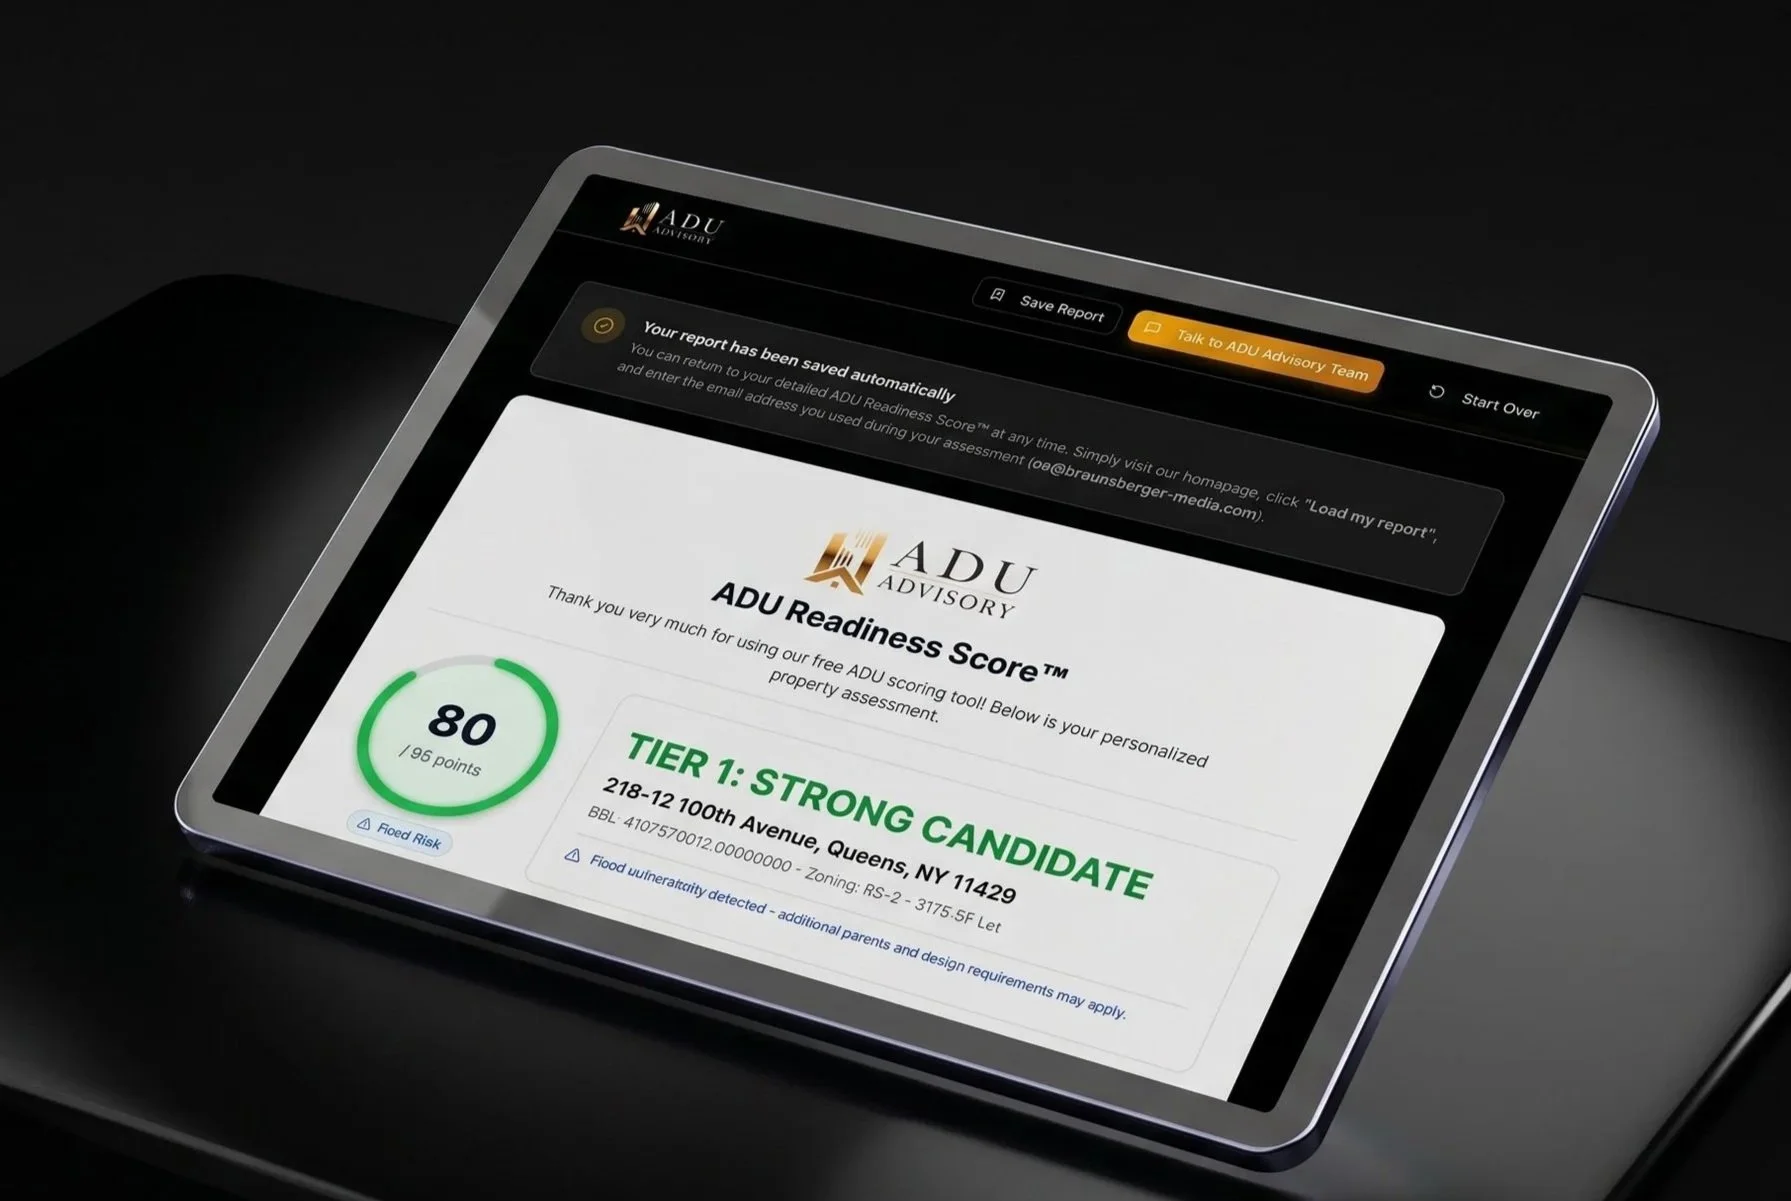
Get your free Score: score.aduadvisory.com
More Articles
We’re breaking down the 131 remaining permits, why availability in your school district matters, the Town’s $100,000 financing opportunity, and what it all could mean for your property, and if it’s worth it.
Applications for the 2026 Construction Assistance Program close August 21, 2026.
The real question is whether the financing, rental requirements, and long-term use of the ADU make sense together for what you want to accomplish with your property.
A one-family detached house, a lot bigger than most in the city, and a deep rear yard. On paper, a promising ADU candidate. But running a Staten Island family's property through the basic decision checklist — property type and zoning, proposed location, ceiling height and egress in the basement, rear-yard depth and utility runs for a backyard unit — reframed the whole conversation. They came in asking "Can we build an ADU?" and left asking a sharper question.
Most homeowners assume an ADU gets financed like a renovation, but the money question is really about which asset the lender is underwriting. Cash, home equity, construction loans, and renovation mortgages each carry different costs and timelines, and the one that fits depends more on your equity position than on the project itself.
An ADU can create rental income, but the rent number alone won't tell you whether the project works. The smarter question compares likely rent against total project and ownership cost, and the gap between what a homeowner imagines and what it really takes can be larger than expected.
Most homeowners begin with one question: "Can I add an apartment?" A better question is: "Which type of ADU best fits my property?"
There are five common ADU types to consider.
If you received an ADU Readiness Score, you have taken an important first step. The score can indicate whether your property has some of the basic conditions needed for an accessory dwelling unit — but it is not a final determination.
Many NYC homeowners are unaware that they already possess spaces within their properties that could legally generate significant monthly income. With property values and expenses rising, the opportunity to earn between $1,500 and $3,500 each month from unused areas presents a compelling solution.
We empower property owners, professionals, and policymakers with interactive courses, peer support, and open conversation, we aim to educate. This is a space to ask questions, share progress, and grow a movement rooted in practical impact and community driven change.
NYC has embraced the ADU. Queens, Brooklyn, Bronx, and Staten Island residents have a new opportunity to enhance their property value, help their family, and their community. Learn more about ADUs.